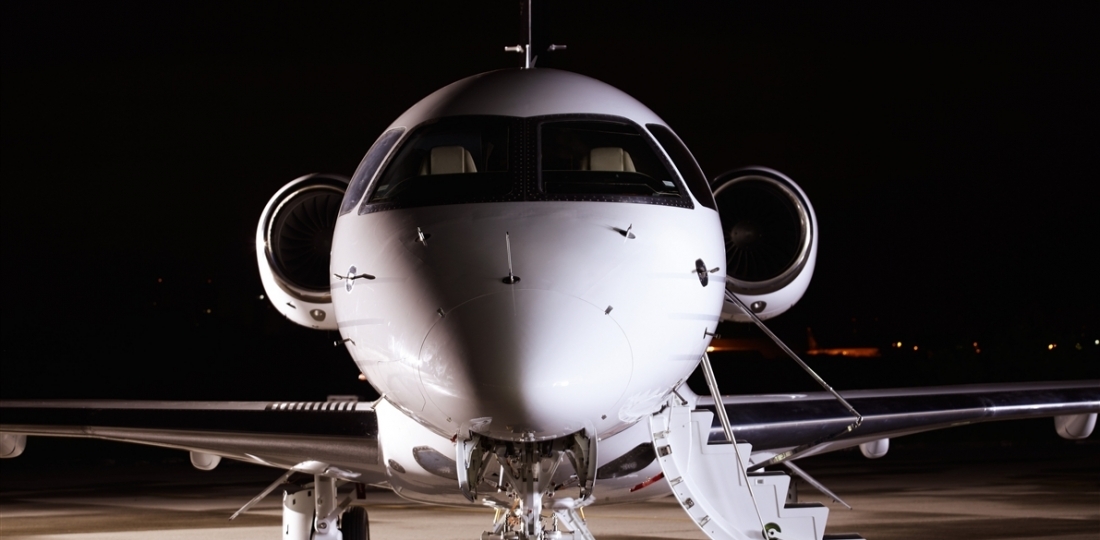
JetNet iQ is still predicting that 744 new business jets will be delivered this year—up from its estimate of 710 last year—but the business aviation data firm is adjusting its 10-year outlook to “reflect recent industry and market developments, especially in the large cabin market.” Thus, it now expects lower delivery volumes and a higher share of aircraft to be delivered to the U.S. over the next decade.
“Counterbalancing the slowdown in ‘globalization’ and at the top end of the market, we continue to believe that the medium jet segment in particular will be quite active,” JetNet iQ managing director Rollie Vincent told AIN. “Business aircraft owners and operators in the U.S. are far and away the most optimistic of any of the markets we are monitoring. This is in sharp contrast to developing and emerging markets such as Brazil, Russia, China and South Africa, where conditions are dragging down the worldwide outlook for new and pre-owned business aircraft sales.”
As a result, pre-owned transactions look to have ended 2015 about 5 percent lower year-over-year on the back of a particularly weak fourth quarter, he said. Although year-end numbers are still being finalized, Vincent said it appears that for-sale inventory plateaued and then rose modestly to about 11.5 percent of the in-service fleet at year-end, up for the first time since the worst of the aftermath of the financial crisis.
“This inventory shift should put even more downwards pressure on aircraft prices in 2016,” he added. “At a 50,000-foot level, the supply of business aircraft remains above demand, based on the imbalance that is apparent in aircraft asking and transaction prices, new aircraft discounting, and lower rates of flight activity compared to pre-crisis levels.”
Vincent noted that buyers continue to have the upper hand and there is “tremendous pressure” on new prices and on residual values of pre-owned aircraft. Soft demand in emerging markets, overcapacity in traditional markets such as North America and Europe and lower pricing all point to the potential for lower new factory deliveries over the next two years, especially at the top of the market, he said.
“Short of any unannounced product improvements and upgrades that might be in the pipeline, near-term decisions regarding lower production rates seem prudent,” Vincent said. “This is especially the case for large-cabin jets that are at a later stage in their product life cycle. Without these decisions, the pressure on sellers to discount will almost certainly increase in 2016.”
As the 10th edition of the Riga Aviation Forum was getting ready to open, 50SkyShades — a long‑standing Media Partner of the event — took the opportunity to sit down with Zigmars Vestfals,...
Airbus has officially unveiled a new delivery center at its Jean‑Luc Lagardère site, northwest of Toulouse, marking a significant milestone in the industrial ramp‑up of the A320 Family. Purpose...
Electra and The Atlas Group today announced a landmark airframe agreement for the EL9 Ultra‑Short aircraft, uniting Electra’s next‑generation design with Atlas’s established aerospace manu...
KVE by Daher is marking its 30th anniversary with the inauguration of a significant expansion of its production facility in The Hague — a development that signals the start of a new acceleration...